IMF report details a financial system with rising risks and vulnerabilities
One of the most striking features of the International Monetary Fund’s Global Financial Stability Report presented to its annual meeting held in Bangkok, Thailand, this week is that the eruption of another financial crisis, following those of 2008 and March 2020, is taken as given.
The issue is not whether it will take place but how can it be prepared for, from where it will emerge, what will be its implications and what measures might be undertaken to try to mitigate its effects.
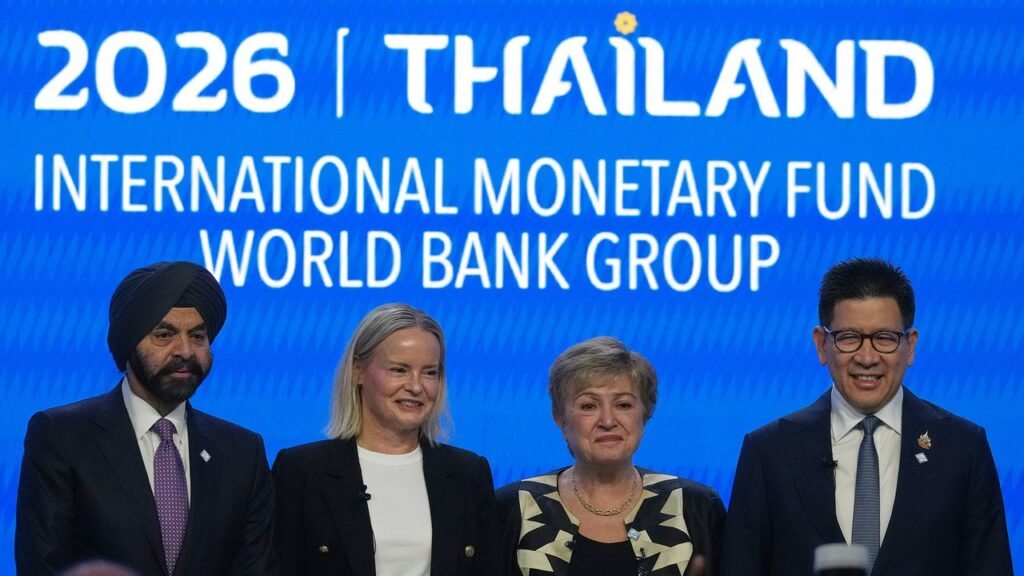
President of the World Bank Group Ajay Banga, Finland Finance Minister Riikka Purra, International Monetary Fund Managing Director Kristalina Georgieva and Thailand Finance Minister Ekniti Nitithanprapa during the annual meetings of the IMF and the WBG in Bangkok, Tuesday, Oct. 13, 2026. [AP Photo/Sakchai Lalit]
However, the report notes that “aggregate resilience” may mask what it calls “pockets of weakness” with banks representing 22 percent of global banking assets classified as “weak,” an increase from 18 percent as per a 2025 stress test. It seems that in the world of the IMF some “pockets” are rather large.
Furthermore, being counted as among the strong in a stress test is not in and of itself a guarantee of stability because of “some banks’ growing interconnectedness with nonbank financial intermediaries [NBFIs, hedge funds and private credit]” that could be a source of “fragility.”
The report notes that loans to NBFIs in the US increased by 18 percent this year while exposures to private equity and private credit rose by 30 percent and while these exposures “do not appear to pose systemic risks on their own, they could become a meaningful source of losses under severe stress.”
“Vulnerabilities also persist among institutional investors through rising liquidity mismatches and concentrated investments.”
This is a reference to the moves by pension funds and insurers to invest more of their funds in longer-term but illiquid assets—they have nearly doubled such holdings over the past decade—to achieve a sufficient rate of return.
In a period of market stress, not necessarily a major crisis, they must obtain cash and turn to the sale of their most liquid assets such as bonds.
“The implications could be significant,” the report explains, “as pension funds and insurers are among the largest investors in financial markets, holding more than one-quarter of publicly traded corporate bonds in the United States and the euro area. Large-scale sales of liquid assets could therefore exacerbate market stress and transmit shocks well beyond the institutions affected directly.”
Such transmission was seen in the March 2020 “dash for cash” when for several days there were no buyers for US government debt—supposedly the safest financial asset in the world—and in the UK bond crisis of October 2022.
Questions about this article? Ask Socialism AI
The report also directs attention to the role of AI spending which has become “an important source of support for the global economy and financial markets” and which has helped to “offset possible negative effects from the war in the Middle East and overall policy uncertainty”—consequences of the actions of the Trump administration which are never directly referenced.
It warns that “weaker or less durable AI investments and profitability could be a shock that triggers a market correction,” that is, a bursting of the bubble.
The report notes that AI capabilities can be delivered at “lower investment levels,” that is cheaper, and that “potential economic gains may not be as large as expected.”
And the turn by the hyperscalers to debt to finance their massive operations could “exacerbate this shock.” From 2024 to the present the hyperscalers’ share of investment-grade bond issuance has risen from less than 1 percent to 10 percent.
Overall, the report notes that the growing sources of leverage in the financing of AI and the acquisition of AI equities “heightens the potential for forced selling and surges in equity volatility and credit spreads in event of lackluster and less durable AI investment and profitability.”
Circular financing in which major AI firms finance their customers, either through equity or credit, could also cause major problems because while investors may be financially sound “distress at key investee firms could present significant ‘wrong-way risk’ to the AI ecosystem.”
This feedback works at two levels: the firm financing the company buying its products suffers a loss of sales revenue and at the same time the value of its equity and credit investment in that company declines.
The extent of the massive speculative gamble involved in circular financing was highlighted by an investigation carried out by the IMF. In a review of 14 such transactions it found that since 2023 about $300 billion had been spent in equity transactions and $650 billion on debt in the expectation of $1.4 trillion in future revenue. Whether such a return is actually realised is another question.
More Stories
Bowing to Washington’s pressure, Sri Lanka and India refuse to provide aid to Iranian ships
Marco Rubio declares West must dominate world, praises colonialism, erases history
US economy and Wall Street increasingly dependent on AI amid concerns over circularity